
Comparison framework
| Method family | Common funding role | Can it receive a withdrawal? | Main points to confirm |
|---|---|---|---|
| Bank transfer | Direct account-to-account payment | Often, if a valid account is accepted | Sender location, NZD support, references, intermediary fees |
| Debit card | Card purchase authorised by your bank | Sometimes as a card credit or refund | Gambling controls, 3-D Secure, card expiry, card-credit support |
| E-wallet | Separate wallet balance linked to bank/card | Product and operator dependent | Wallet currency, funding fee, withdrawal fee, account-name match |
| Prepaid voucher | Fixed-value deposit | Usually not back to the original code | Exit route, remaining voucher balance, KYC |
| Mobile wallet | Tokenised debit card payment | Usually follows the underlying card rules | Device/browser, underlying card, refund destination |
| Cryptoasset | Transfer to an address on a named network | Possible only when both ends support the same asset/network | Address, network, custody, fees, conversion and price movement |
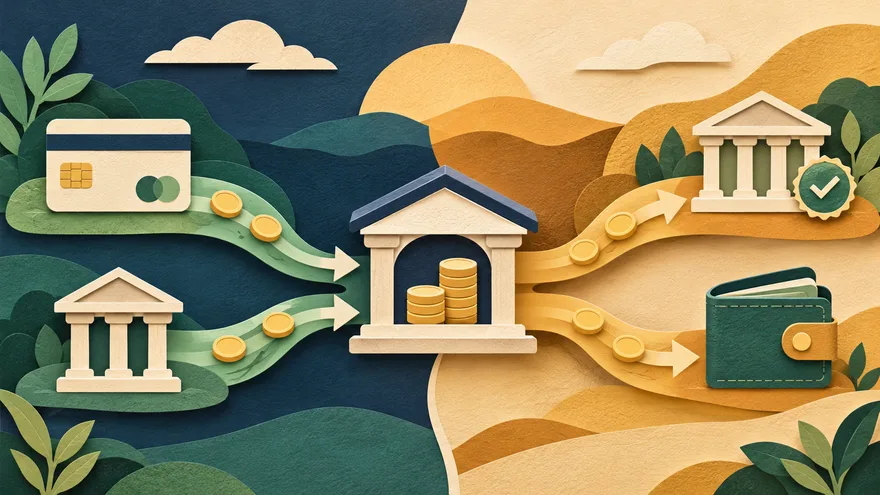
“Instant” normally describes authorisation or network movement, not the complete route. A deposit can appear in seconds because the operator accepts a payment confirmation. A withdrawal begins later, after account and legal checks, and may use another rail.
New Zealand's 2026 rules
Regulation 20 says a licensed operator must allow only one registered deposit method at a time and cannot let it change within 24 hours of registration. It must allow a different withdrawal method. This matters because a deposit-only tool does not have to become an impossible exit. The regulations also require monetary values related to the platform to be displayed in NZD.
Do not treat those requirements as proof that every currently accessible cashier complies. During the transition, no public licence register of approved brands had yet been published when this page was checked.
Four checks before money moves
- Direction: find separate deposit and withdrawal lists. A logo in the deposit screen proves only that direction.
- Ownership: the account, card or wallet should be in the same legal name as the player account. Never use someone else's payment method to avoid a check.
- Currency: record whether the cashier balance, funding instruction and destination are all NZD. Conversion can happen at more than one stage.
- Evidence: save the terms, amount, reference, timestamp and status. Do not send identity documents by an unverified email or chat link.
Which page next?
Use bank transfer for account-to-account stages, debit cards for authorisation and refunds, e-wallets for the extra wallet-to-bank leg, prepaid vouchers for deposit-only planning, or crypto payments for network and custody risk. The deposit versus withdrawal guide turns those pieces into one route.
FAQ
Does a familiar logo prove a method works in New Zealand? No. It may be a generic page, a deposit-only integration, or unavailable to your account. Confirm the live cashier and product's own regional terms.
Does seven-day NZ banking make every transfer instant? No. Payments NZ's change concerns participating domestic banks. An operator may still review a request, send from overseas or use an intermediary.
Are credit cards treated like debit cards? No. The new regime restricts credit-based funding. This site discusses debit cards separately and does not recommend gambling with borrowed money.