
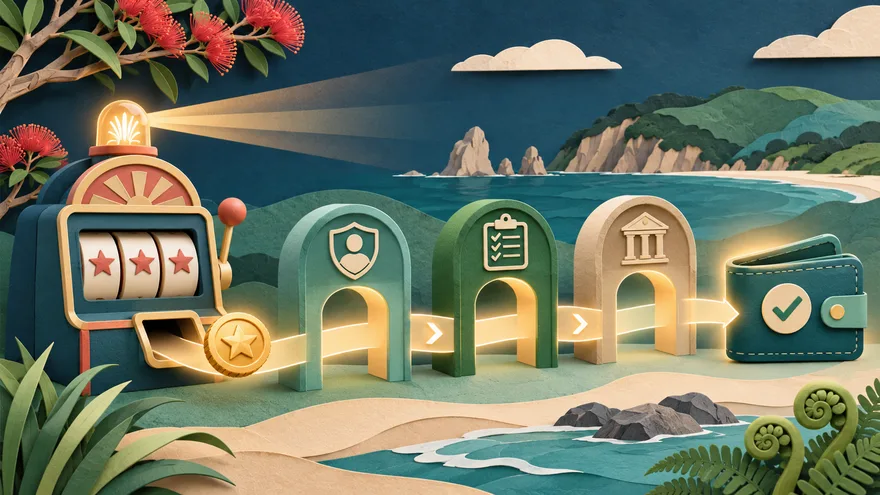
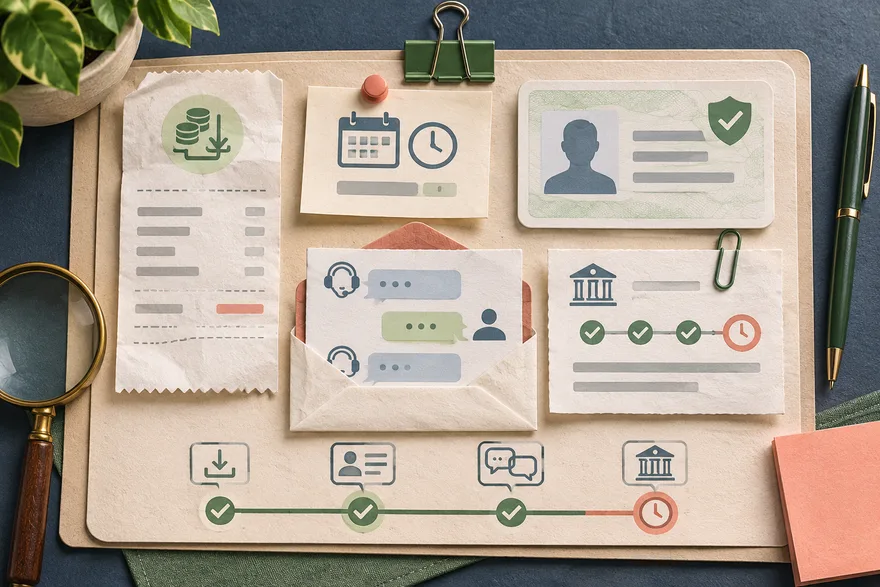
Withdrawal timeline
| Status | Likely owner | Best evidence | Next step |
|---|---|---|---|
| Requested | Operator cashier | Request ID and timestamp | Read the stated review period |
| Action required | Customer/operator | Exact document or rule request | Respond only through a verified secure route |
| Pending/reviewing | Operator | Status history and support case | Ask what condition remains and for the relevant clause |
| Approved | Operator | Approval message | Ask whether funds have actually been sent |
| Sent | Payment rail | Transaction/transfer reference | Use the rail's trace process |
| Received | Bank/wallet | Statement and received currency | Reconcile gross, conversion and deductions |
The 2026 regulations say licensed operators must complete a withdrawal without undue delay after legal requirements are satisfied. They also prevent a customer from cancelling a pending return of funds. Those protections belong to the licensed regime; they should not be projected onto an unverified operator during the transition.
What can lawfully pause a withdrawal?
Identity, age, location, payment ownership, anti-money-laundering review and a genuine security concern can require checks. A request should be specific. “Under review” with no condition, evidence request or timescale is not enough information for the customer to solve the problem.
Do not falsify a document, edit a statement, use another person's account or open a new route to avoid a check. That can create a larger compliance problem and reduce the chance of resolving the original request.
Choose the right diagnostic page
- How long? separates operator review from payment transit.
- Pending provides a stage-by-stage question set.
- Declined turns a rejection into an evidence checklist.
- Verification explains safe document handling.
- Fees and FX reconciles sent and received amounts.
- Same-method rule distinguishes source-of-funds controls from an absolute rule.
- Complaints and records builds a concise case file.
Transition warning for December 2026
DIA says providers that have not applied for a licence must cease offering online casino gambling in New Zealand from 1 December 2026. A provider leaving the market should still let customers contact it, withdraw uncommitted funds and close accounts; market exit is not an excuse to avoid obligations. If you hold a balance, use the authenticated withdrawal route and preserve records before access changes.
FAQ
Does “approved” mean the bank has the money? Not necessarily. Ask for the sent date and payment reference.
Can I cancel a pending withdrawal and keep playing? The new licensed-market regulations prevent cancellation while funds are being returned. Avoid any interface that pressures you to reverse a cash-out.